Add TOPKHOJ as a Preferred Source on Google
Ever since Elon Musk acquired Twitter in 2022, his stated endgame was never just a social media square-it was WeChat for the Western world. That ambition has officially transitioned from regulatory paperwork into live consumer software with the broader X Money launch. Integrated directly into the main X interface, the new digital payments and banking service transforms user profiles into transaction nodes, letting subscribers store cash, transfer funds instantly, and spend in the real world.
Rather than attempting to secure an independent commercial banking charter from scratch, X Payments LLC has built its fintech layer on top of established financial infrastructure.
Primary deposit accounts and regulatory clearing rails are handled by Cross River Bank (Member FDIC), while payment routing and debit card issuance run over Visa’s global network.
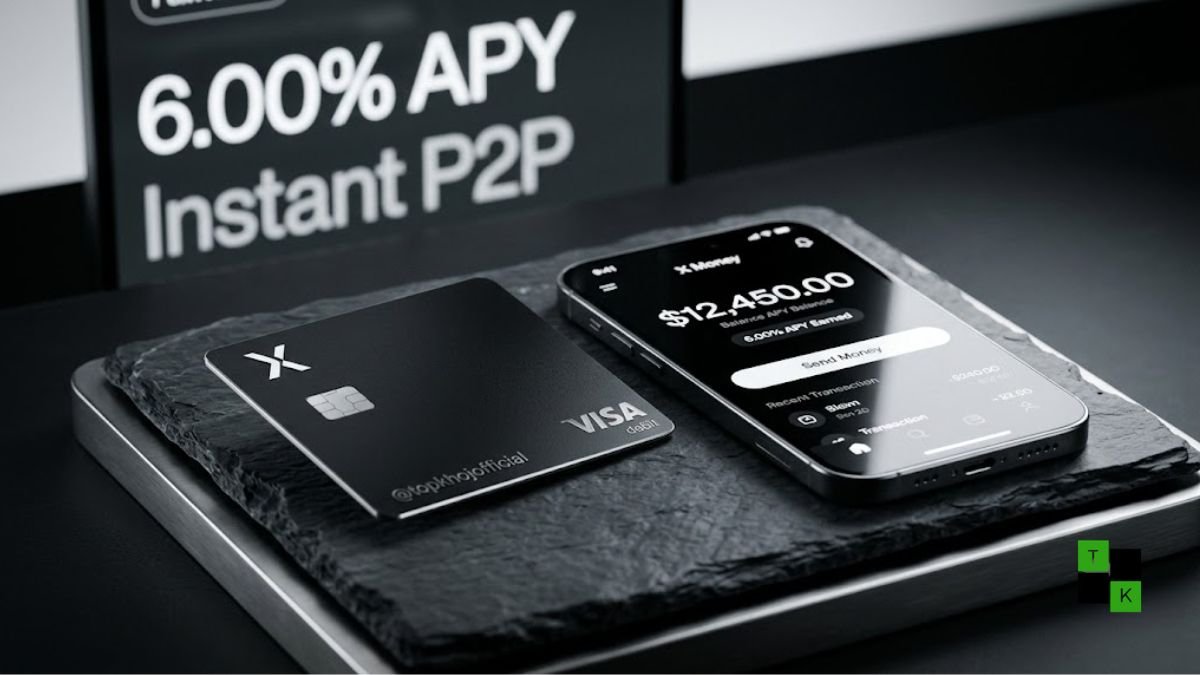
The service offers an aggressive combination of consumer incentives: free peer-to-peer payments via @handle, up to 6.00% APY on cash deposits, a physical metal Visa debit card with 3% cashback, and two-day early direct deposit.
However, gating these perks behind paid subscriptions and navigating US regulatory boundaries introduces several key caveats.
Core Financial Rails: Cross River Bank & FDIC Pass-Through Coverage
The most critical distinction for potential users is structural: X is not a bank. To legally offer interest and custody funds, X operates through a standard fintech partnership model:
- Cross River Bank Partnership: All primary checking and deposit balances reside with New Jersey-based Cross River Bank, a regulated FDIC-insured institution. This ensures individual deposit accounts receive standard $250,000 FDIC insurance protection against bank insolvency.
- Up to $10M Extended Cash Sweep Program: For high-net-worth creators and business accounts holding substantial capital, X Money includes an automated multi-bank sweep program. Excess deposits are swept into a network of partner FDIC banks, extending pass-through deposit insurance up to $10 million.
- Security & Authentication: To prevent account takeovers, X Money transactions are separated from standard social logins. Accounts support passkey authentication, hardware security keys, biometric prompts, and user-configurable spending caps per transaction.
In-App P2P Payments: Turning Your @Handle into a Routing Number
Sending money online typically requires swapping phone numbers, email addresses, or separate Cashtags. X Money eliminates that friction by tying payments directly to the social graph:
- Free Instant Transfers: Users can send, request, and split money with any other X user inside direct messages or through dedicated payment sheets. Because payments resolve internally or route via Visa Direct, transfers are instant and incur zero transaction fees.
- Early Direct Deposit: By providing standard routing and account numbers, users can route their employer paychecks into X Money. Eligible direct deposits arrive up to two days ahead of standard paydays.
- Bill Pay, Wires, and Physical Checks: Far beyond casual Venmo-style peer transfers, the account supports traditional banking operations, including outgoing domestic wire transfers, recurring bill payments, and the ability to mail physical paper checks directly from the app.
The 6.00% APY Incentive and The Premium Subscription Gate
To entice users to move their idle cash out of zero-interest checking accounts and third-party digital wallets, X is leveraging an eye-catching interest rate:
- Up to 6.00% APY on Balances: X Money advertises an Annual Percentage Yield reaching 6.00% on held cash balances-a rate that substantially beats standard high-yield savings accounts and traditional retail bank rates.
- The Subscription Catch: Access to X Money is strictly restricted to paid X Premium and Premium+ subscribers. While Premium+ users automatically qualify for the full 6.00% APY, base Premium subscribers must receive at least $1,000 in qualifying direct deposits within a rolling 34-day window to unlock the top rate.
- Variable Rate Disclaimer: Like all fintech yield promotions, the 6.00% APY is variable and subject to change based on Federal Reserve benchmark adjustments and macroeconomic conditions.
The Physical X Card: Metal Visa Debit with 3% Cashback
Alongside the digital wallet, subscribers can order a tangible debit card designed to turn social identity into a status accessory:
- Matte Metal Construction: Eligible subscribers receive a physical metal Visa debit card. Users can customize how their legal name appears and choose whether to display their X @handle on the card face.
- 3% Cashback on Eligible Spend: Card purchases earn an impressive 3% cashback on eligible categories, credited directly back into the user’s X Money wallet balance.
- Zero Foreign Transaction & Free Global ATMs: The card charges zero foreign transaction fees when traveling abroad and offers global ATM withdrawal fee reimbursements within three business days.
- Apple Wallet and Google Pay: For contactless mobile payments, the card integrates natively into Apple Wallet and Google Wallet.
X Money vs. Apple Cash vs. Venmo vs. Traditional Banking
| Feature Dimension | X Money (X Payments) | Apple Cash / Apple Savings | Venmo (PayPal) | Traditional Bank (Chase / BoA) |
| Banking Partner | Cross River Bank (Member FDIC) | Goldman Sachs Bank USA | The Bancorp Bank | Direct Chartered Bank |
| Annual Percentage Yield | Up to 6.00% APY (Variable) | ~4.10% – 4.40% APY | 0.00% (Standard Balance) | 0.01% – 0.05% |
| P2P Transfer Identifier | Social @Handle / Direct Messages | Phone / Apple ID / Messages | @Username / Phone / QR | Account & Routing Numbers |
| Physical Debit Card | Custom Metal Visa Card | Titanium Apple Card (Credit Only) | Plastic Mastercard Debit | Standard Plastic / Metal Debit |
| Debit Cashback Reward | 3% on Eligible Purchases | None on Debit (1-3% Apple Card) | Up to 3% Select Categories | None to 1% Basic Perks |
| ATM Fee Policy | Free Global ATM Reimbursements | N/A (No Physical Debit Card) | $2.50 Out-of-Network Fee | $2.50 – $5.00 Out-of-Network |
| Direct Deposit Timing | Up to 2 Days Early | Standard ACH | Up to 2 Days Early | Standard Payday |
| FDIC Coverage Limit | Up to $10M (Via Cash Sweep) | $250,000 (Standard FDIC) | Up to $250,000 (With Direct Dep.) | $250,000 Per Depositor |
| Prerequisites / Costs | Requires X Premium (~$8–$16/mo) | Free (Requires iOS Hardware) | Free (Optional Paid Upgrades) | Minimum Balances / Monthly Fees |
Read Also: X Video Kickstart Bonus: Earn $500–$5,000 for 15 Videos
The Regulatory Map and Potential Pitfalls
While the product promises convenience, operating a financial ecosystem inside a volatile social network introduces notable risks:
- State Licensing Gaps: X Payments LLC has secured money transmitter licenses across more than 40 US states and territories. However, key financial jurisdictions-including New York and Massachusetts-remain pending regulatory approvals, meaning residents in those states cannot currently activate accounts.
- International Roadblock (India & Europe): The service is strictly US-only at launch. Users in India, the UK, and the EU cannot open X Money USD accounts or link local bank accounts yet, though international expansion is reportedly planned for later stages once regional financial clearances are obtained.
- The Account Suspension Dilemma: In traditional banking, an argument on social media does not endanger your checking account. On X, financial access is tethered directly to your social profile. While funds remain legally protected at Cross River Bank, losing access to an X account due to terms-of-service violations could create major logistical hurdles for recovering access to funds.
- No Native Crypto Trading Yet: Despite widespread speculation that X Money would launch with Dogecoin or Bitcoin integration, the initial product is 100% fiat-based, focusing entirely on USD balances, ACH transfers, and Visa payment rails.
By delivering FDIC-insured deposits, high yields, and a physical metal card directly to verified subscribers, X Money proves that Elon Musk’s super-app strategy has moved from concept to reality.
Whether mainstream consumers will trust their paychecks to the same platform where they scroll daily headlines remains the biggest question of this ambitious fintech rollout.
🚨 Stay Updated with TopKhoj! 🚨
Get the latest tech news, deals, and exclusive offers first!
📰 Visit News Section📲 Join our Telegram Channel for real-time updates and best deals!
🔗 Join Telegram Now💡 Stay informed and never miss a great deal with TopKhoj!
⚠️ Disclaimer: Any link provided in the article related to a product or service will redirect you to our affiliate partner(s)' website, which are affiliate links. This means that if you make a purchase through these links, we may earn a commission at no extra cost to you. This commission helps support our blog and our work.
🔔 All prices mentioned above are subject to change based on current offers and availability on e-commerce platforms. Please check the latest price and product details on the product page before making a purchase.